
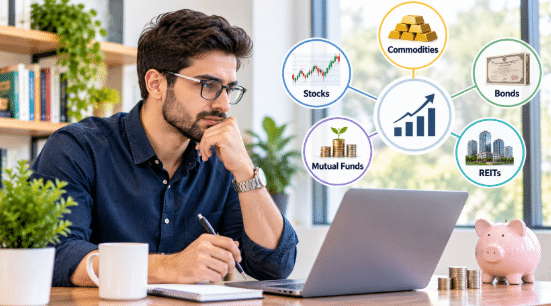
Australians have a well-known soft spot for property. It’s tangible, familiar, and feels safe. But a portfolio that’s all bricks and no balance can hurt when the housing market hits a rough patch. Spreading investments across different asset classes won’t eliminate risk – nothing does – but it tends to smooth out the bumps and give you better footing over time. Whatever stage you’re at, knowing how the main options actually work is a reasonable place to start.
Exchange-Traded Funds: An Easy Entry Point
ETFs are probably the lowest-friction way into investing for someone who doesn’t want to pick individual stocks. You buy one unit, and you’ve effectively got a slice of dozens, sometimes hundreds, of companies at once. That built-in spread is the main appeal – you’re not betting everything on one business doing well.
Choosing one still requires some thought. Are you after broad market exposure, a particular sector, something international? Worth figuring out before you commit. Australian ETFs can also carry franking credit benefits on dividends, which is a tax angle worth understanding – it can make a meaningful difference to what you actually take home after tax.
Stocks and Equities: Growth with Greater Risk
Owning shares directly is still how a lot of Australians build wealth, and there’s good reason for it. You get two potential income streams: the share price going up over time, and dividends paid along the way. The ASX has generally rewarded patience, though that varies a lot depending on which companies and sectors you’re in.
It takes more work than buying an ETF. You’re looking at things like earnings trends, debt, how a company sits relative to its competitors, and what’s happening in the broader industry. Prices can move fast and sometimes for reasons that have nothing to do with the underlying business. If that kind of volatility makes you anxious, equities might need to be a smaller part of the mix – or not yet.
Bonds and Fixed Income: Stability for Conservative Investors
Bonds are a different animal entirely. You’re lending money – to a government or a company – and in return you get regular interest payments, then your principal back when the bond matures. Government bonds sit at the lower-risk end. Corporate bonds pay more, because there’s more chance something goes wrong.
Two things can bite you here. If interest rates rise, existing bond prices tend to fall – that’s interest rate risk. And credit risk is just the question of whether whoever borrowed your money can actually pay it back. For people getting closer to retirement, or anyone who wants something predictable sitting alongside more volatile holdings, fixed income can do a lot of steadying work.
Commodities and Precious Metals: A Hedge Against Inflation
Gold has been a go-to in uncertain times for a long time, and plenty of Australian investors still keep some as a hedge. Silver sits in a similar space. Then there are agricultural commodities and energy – each one driven by its own set of forces: seasons, geopolitics, shipping lanes, supply disruptions.
What makes commodities worth thinking about is that they don’t always move in step with shares or bonds. When equity markets drop, commodities sometimes don’t – or even go up. That’s the point. It’s not that they always perform well on their own; it’s that they tend to zig when other things zag.
Alternative Investments: Beyond the Traditional Mix
Peer-to-peer lending, crowdfunding, managed funds, infrastructure – there’s a wider range of options now than there used to be, and not all of them require going through public markets. Managed funds and investment trusts hand the decision-making to someone else, which suits investors who’d rather not be watching prices daily. Private equity and infrastructure can give you exposure to things that don’t show up on any exchange.
Crypto fits loosely in this category too. The volatility is real, the regulatory picture is still shifting, and it’s not for everyone. Worth knowing what you’re walking into before committing anything significant.
Building a Balanced Future
There’s no asset class that always wins. What diversification actually does is reduce the chance that one bad run wipes out everything else. A mix of shares, bonds, ETFs, commodities, and alternatives isn’t a magic formula – but it’s a more resilient base than putting it all in one place. If you’re not sure how to put that together for your specific situation, talking to someone offering wealth management in Canberra is a practical step – they can help you build something that fits your goals and timeline, not just a generic allocation off a template.
